20.96M

Payroll employees · Q2 2026

8.3%

ILO unemployment rate · Q2 2026

−0.1%

Quarterly payroll change · Q2 2026

UTC+1 / +2

CET · CEST in summer

LOCAL KNOWLEDGE. GLOBAL AMBITION.

Your next chapter starts here.

France offers a large, highly skilled workforce, strong infrastructure, and direct access to the European market. In Q2 2026, payroll employment stood at about 20.96 million and the ILO unemployment rate was 8.3%. Start your hiring plan by choosing the right relationship for each role, then align contracts, payroll, and benefits with the French Labour Code, social-security rules, and any applicable collective bargaining agreement.

Country Snapshot

What To Know

Capital

Paris

Currency

Euro (EUR)

Euro (EUR)

Working language

French; English is common in international business and technology teams.

French; English is common in international business and technology teams.

Time zone

Central European Time (UTC+1), with Central European Summer Time (UTC+2).

Central European Time (UTC+1), with Central European Summer Time (UTC+2).

Hiring approach

Local employment for ongoing roles under organizational direction; independent contracts for genuinely autonomous services. French authorities examine working reality, not only the contract label.

Local employment for ongoing roles under organizational direction; independent contracts for genuinely autonomous services. French authorities examine working reality, not only the contract label.

Payroll planning

Define gross salary, collective agreement, working time, benefits, DSN payroll reporting, social contributions, withholding tax, paid leave, and occupational-health requirements before onboarding.

Define gross salary, collective agreement, working time, benefits, DSN payroll reporting, social contributions, withholding tax, paid leave, and occupational-health requirements before onboarding.

BG
BG
BG
BG

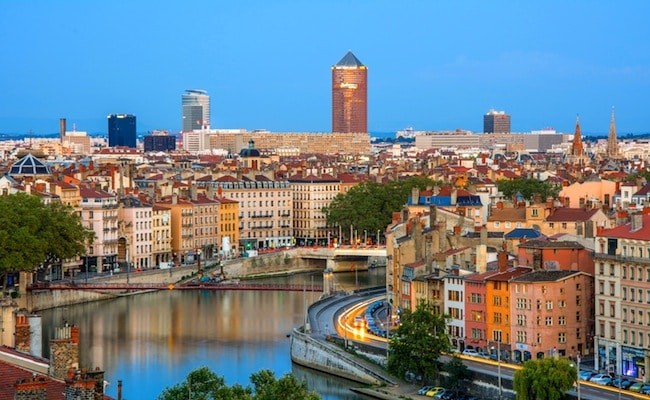
Lyon. A different perspective on your next hiring market.

BUILD YOUR LONG-TERM TEAM

Hiring employees in France

For roles that sit inside your organization, start with a French employment arrangement. Budget for the full employment package and identify who will handle hiring declarations, payroll, DSN reporting, social contributions, withholding tax, occupational medicine, and ongoing administration.

Employment Essential

At a Glance

Employment terms

The French Labour Code and applicable collective agreement govern the relationship. Written contracts are essential for fixed-term, part-time, and other special arrangements. The standard statutory workweek is 35 hours. From June 1, 2026, the gross SMIC is €12.31 per hour or €1,867.02 per month for 151.67 hours.

The French Labour Code and applicable collective agreement govern the relationship. Written contracts are essential for fixed-term, part-time, and other special arrangements. The standard statutory workweek is 35 hours. From June 1, 2026, the gross SMIC is €12.31 per hour or €1,867.02 per month for 151.67 hours.

Salary payments

Employees are generally paid monthly in euros with an itemized payslip. Employers run payroll withholding, make the pre-employment declaration, and report pay and social contributions through the monthly Déclaration Sociale Nominative (DSN).

Employees are generally paid monthly in euros with an itemized payslip. Employers run payroll withholding, make the pre-employment declaration, and report pay and social contributions through the monthly Déclaration Sociale Nominative (DSN).

Annual bonus

No universal statutory 13th-month bonus applies, but collective agreements and contracts frequently provide bonuses, profit sharing, meal vouchers, or other benefits.

No universal statutory 13th-month bonus applies, but collective agreements and contracts frequently provide bonuses, profit sharing, meal vouchers, or other benefits.

Paid annual leave

Employees accrue 2.5 working days of paid leave per month, normally five weeks per year. Public-holiday treatment, RTT days, and additional leave depend on the working-time arrangement and collective agreement.

Employees accrue 2.5 working days of paid leave per month, normally five weeks per year. Public-holiday treatment, RTT days, and additional leave depend on the working-time arrangement and collective agreement.

Employer cost planning

Budget for employer social contributions, complementary pension, unemployment insurance, workplace-accident coverage, health insurance, transport reimbursement, paid leave, payroll levies, and any collective-agreement benefits.

Budget for employer social contributions, complementary pension, unemployment insurance, workplace-accident coverage, health insurance, transport reimbursement, paid leave, payroll levies, and any collective-agreement benefits.

Employment framework: Code du travail, Code de la sécurité sociale, applicable collective agreements, URSSAF rules, and DSN requirements. Exact costs vary by salary, company size, sector, location, exemptions, and benefit design.

Employer of Record

Explore an employment route with Rise.

Rise EOR manages local employment contracts, payroll, and compliance in supported markets. Discuss your France hiring plan with the team to confirm availability, timing, and the right setup.

Confirm France EOR availability with Rise before making an offer, including the employing entity, collective agreement, benefits package, and onboarding timeline.

WORK WITH INDEPENDENT SPECIALISTS

Hiring contractors in France

Bring independent expertise into your business with clear deliverables, documented terms, and a reliable payment process. French authorities can reclassify an engagement where the relationship shows legal subordination, employee-style direction, or integration into the client’s organization.

Set Up For Success

Your Contractor Checklist

Scope & autonomy

Agree on deliverables, timelines, and independent working practices. Avoid employee-style control, fixed hours, exclusivity, and organizational integration where the relationship is intended to remain independent.

Agree on deliverables, timelines, and independent working practices. Avoid employee-style control, fixed hours, exclusivity, and organizational integration where the relationship is intended to remain independent.

Service agreement

Document fees, currency, payment timing, VAT treatment, intellectual property, confidentiality, data protection, liability, and termination terms.

Document fees, currency, payment timing, VAT treatment, intellectual property, confidentiality, data protection, liability, and termination terms.

Tax & invoicing

Confirm the contractor’s SIREN or SIRET, business status, VAT number or exemption, and ability to issue a compliant invoice. For larger engagements, collect required vigilance documentation and refresh it as required.

Confirm the contractor’s SIREN or SIRET, business status, VAT number or exemption, and ability to issue a compliant invoice. For larger engagements, collect required vigilance documentation and refresh it as required.

Onboarding

Collect identity and payment details, signed agreements, registration evidence, professional insurance where relevant, and the documentation your engagement requires.

Collect identity and payment details, signed agreements, registration evidence, professional insurance where relevant, and the documentation your engagement requires.

Payment preferences

Agree on supported withdrawal options and make fees, conversion, and settlement expectations clear. Confirm whether the contractor wants funds received in EUR, USD, or a supported digital asset.

Agree on supported withdrawal options and make fees, conversion, and settlement expectations clear. Confirm whether the contractor wants funds received in EUR, USD, or a supported digital asset.

Global Contractor Pay

One place to manage payday.

Onboard your contractors, organize payments, and fund payroll in USD or supported stablecoins. Give contractors flexibility over supported withdrawals, including EUR.

Agent of Record

More support for your engagements.

Add contractor classification, contracts, onboarding, and compliance support. Ask Rise about the scope of coverage for your France team.

BG
BG
BG
BG

Bordeaux. Local character, connected to a world of opportunity.

PLAN BEYOND THE HEADLINE SALARY

What does hiring in France actually cost?

Start with the agreed gross salary or contractor fee, then separate business costs from worker deductions. The examples below use euros, apply indicative 2026 rates, and illustrate a budget rather than a final payslip or quote.

BUSINESS BUDGET

Employer costs

Cost

Budget Basis

Gross salary

100% of agreed pay

100% of agreed pay

Employer social contributions

Often around 40% to 45% of gross salary for professional roles before reductions, caps, sector differences, and company-specific levies.

Often around 40% to 45% of gross salary for professional roles before reductions, caps, sector differences, and company-specific levies.

Complementary pension

AGIRC-ARRCO contributions are shared between employer and employee, with rates depending on earnings bands.

AGIRC-ARRCO contributions are shared between employer and employee, with rates depending on earnings bands.

Health and welfare

Employer-funded complementary health insurance and, where applicable, disability and death cover.

Employer-funded complementary health insurance and, where applicable, disability and death cover.

Other payroll costs

May include workplace-accident contributions, mobility payment, apprenticeship levy, training contributions, transport reimbursement, meal benefits, and collective-agreement items.

May include workplace-accident contributions, mobility payment, apprenticeship levy, training contributions, transport reimbursement, meal benefits, and collective-agreement items.

Rise service fees

Request a separate platform or EOR/AOR quote, subject to France coverage.

Request a separate platform or EOR/AOR quote, subject to France coverage.

EMPLOYEE PAYSLIP

Employee deductions

Deduction

2026 TREATMENT

Social contributions

Employee deductions often total about 20% to 23% of gross salary, depending on pay level, pension bands, and benefit elections.

Employee deductions often total about 20% to 23% of gross salary, depending on pay level, pension bands, and benefit elections.

CSG and CRDS

Levied on a defined contribution base, with deductibility depending on the component.

Levied on a defined contribution base, with deductibility depending on the component.

Income tax

Withheld at source using the personalized or neutral rate supplied by the tax administration.

Withheld at source using the personalized or neutral rate supplied by the tax administration.

Net pay

Gross salary less employee social deductions, income-tax withholding, and any employee-elected benefits.

Gross salary less employee social deductions, income-tax withholding, and any employee-elected benefits.

WORKED EXAMPLE · €5,000 GROSS / MONTH

One salary. Two different numbers.

Employer monthly budget equivalent

About €7,100

Using an illustrative 42% employer burden

Employee pay before income tax

About €3,900

Using illustrative 22% employee deductions

Employer Budget Component

Illustrative Monthly Amount

Monthly gross salary

€5,000

Employer contributions and payroll costs, illustrative 42%

€2,100

Monthly budget equivalent

€7,100

Actual French payroll is highly salary-, sector-, location-, and company-specific. This illustration excludes Rise fees, discretionary benefits, paid-leave funding effects, termination exposure, and special reductions. Obtain a role-specific simulation before making an offer.

Contractor costs: what the business pays, what the contractor keeps.

A contractor’s invoice is business revenue. The contractor needs to budget for social contributions, income tax, VAT administration, insurance, time off, and operating expenses before treating it as spendable income.

Cost Item

Hiring Business

Contractor

Service fee

Agreed invoice plus 20% VAT where applicable.

Agreed invoice plus 20% VAT where applicable.

Receives the agreed fee before their own contributions, tax, and costs.

Tax & social coverage

No employee payroll contributions apply to a genuine independent provider. Reclassification can create back contributions, employment rights, and penalties.

No employee payroll contributions apply to a genuine independent provider. Reclassification can create back contributions, employment rights, and penalties.

Declares turnover or profit, pays social contributions and income tax under the chosen status, and manages VAT where required.

Payment & administration

Add the agreed Rise plan, payment fees, and any conversion costs.

Add the agreed Rise plan, payment fees, and any conversion costs.

Confirm who bears withdrawal and conversion fees.

Benefits & operating costs

Include any negotiated allowances in the contract.

Include any negotiated allowances in the contract.

Set aside amounts for professional insurance, equipment, accounting, retirement, and non-billable time.

Independent tax: what a French freelancer pays

Component

2026 Rate or Rull

Micro-BIC services

Social contributions are generally 21.2% of turnover for qualifying commercial or artisan services, plus the applicable professional-training contribution.

Social contributions are generally 21.2% of turnover for qualifying commercial or artisan services, plus the applicable professional-training contribution.

Micro-BNC services

From January 2026, social contributions are generally 25.6% of turnover for qualifying non-regulated liberal services, plus the professional-training contribution.

From January 2026, social contributions are generally 25.6% of turnover for qualifying non-regulated liberal services, plus the professional-training contribution.

Income tax

Taxed under the household’s progressive income-tax scale after the applicable micro allowance, or through an optional versement libératoire when eligibility conditions are met.

Taxed under the household’s progressive income-tax scale after the applicable micro allowance, or through an optional versement libératoire when eligibility conditions are met.

VAT

20% standard rate when VAT applies. The franchise en base can exempt qualifying small businesses, subject to current turnover thresholds and activity rules.

20% standard rate when VAT applies. The franchise en base can exempt qualifying small businesses, subject to current turnover thresholds and activity rules.

Reporting

Micro-entrepreneurs declare turnover monthly or quarterly to URSSAF and report annual income to the tax administration.

Micro-entrepreneurs declare turnover monthly or quarterly to URSSAF and report annual income to the tax administration.

Other structures

Entreprise individuelle, EURL, SASU, and regulated professions follow different contribution, corporate-tax, and remuneration rules.

Entreprise individuelle, EURL, SASU, and regulated professions follow different contribution, corporate-tax, and remuneration rules.

Contractor Example

€5,000 invoiced per month

At €60,000 of annual turnover, a qualifying micro-BNC provider using the illustrative 25.6% social-contribution rate would set aside about €1,280 per month, leaving €3,720 before income tax, VAT settlement, professional-training contribution, payment fees, business expenses, and personal reserves.

This is not equivalent to an employee’s net salary: the contractor example includes no paid leave, unemployment protection, employer-funded benefits, or severance rights. Micro-enterprise eligibility and VAT treatment must be checked against the rules in force.

Make Your Budget Specific

Get a breakdown for your actual hire.

Share the role, location, gross salary or contractor fee, collective agreement, benefits, business status, and preferred payment method. Ask Rise to separate statutory costs, service fees, and payment costs in your quote.

THE RISE ADVANTAGE

A better payday. A better team experience.

Give your global workforce more choice in how they receive their earnings, with payroll built around the way people work.

Daily payroll. More flexibility.

With daily pay schedules, eligible employees can receive pay more frequently and better align income with everyday expenses.

Mon

Tue

Wed

Thu

Fri

Daily payroll is available through Rise’s US Direct Payroll product. Confirm eligibility, state pay-frequency and final-pay rules, and setup with Rise.

Hybrid payroll. More choice.

Connect traditional and crypto payments. Fund payroll in USD, USDC, or USDT, with supported local-currency and crypto withdrawal options for your team.

USD

USDC

USDT

Options depend on location and engagement type. US employee wages must be paid in US dollars through compliant methods under federal and state wage-payment law; crypto withdrawals are a post-payroll option and do not replace those obligations.

Rise to the

challenge.

moment.

task.

opportunity.

challenge.

challenge.

Compliantly hire, onboard, and pay an entire borderless team, right from Rise

Rise to the

challenge.

moment.

task.

opportunity.

challenge.

challenge.

Compliantly hire, onboard, and pay an entire borderless team, right from Rise

Rise

to the

challenge.

moment.

task.

opportunity.

challenge.

challenge.

Compliantly hire, onboard, and pay an entire borderless team, right from Rise